In Part 1, we audited our investor circle of competence. In Part 2, we analyzed founder resilience and executive team friction. In Part 3, we unpacked unit economics and cap table mechanics. In Part 4, we detailed active governance, follow-on reserves, and exit engineering. In Part 5, we learned how to negotiate side letters and deal terms when a term sheet is already on the table. In Part 6, we covered non-intrusive post-investment monitoring and advisory frameworks.
Now, in Part 7, we step back from individual deal dynamics to examine the overarching architecture of successful early-stage investing: Portfolio Construction, Risk Distribution, and Fund Math.
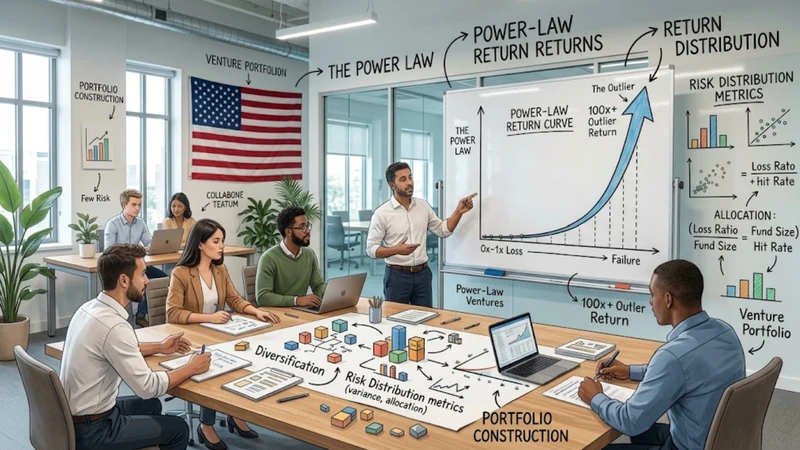
Evaluating a single startup in isolation—no matter how thorough your due diligence—is statistically incomplete. Early-stage venture returns are governed by the power law, where a tiny percentage of investments generate the overwhelming majority of total returns. To build sustainable wealth in early-stage markets, your macro portfolio strategy matters just as much as your micro deal selection.
1. Embrace the Power Law of Early-Stage Returns
In early-stage investing, returns are non-normal and heavily skewed. You cannot build a winning venture portfolio by aiming for consistent "singles and doubles."
The Return Distribution Reality: In a typical early-stage portfolio of 20 investments, expect 10 to fail completely (0x–1x return), 5 to break even or return modest capital (1x–3x), 3 to perform well (3x–10x), and 1 or 2 home runs (20x+) that return the entire pool of capital and generate the fund's net gains.
The Scale Requirement: Every company you underwrite must have the theoretical potential to return your entire fund or allocated check capital single-handedly. If a company's total addressable market (TAM) caps its maximum potential outcome at a 3x return, it does not fit the risk-return profile of seed-stage investing.
2. Dynamic Portfolio Sizing and Capital Deployment
Writing random check sizes as deals present themselves is a fast route to capital depletion. Portfolio strategy requires clear check-size discipline and vintage diversification.
Minimum Diversification Threshold: A statistical minimum of 20 to 25 investments across 3 to 4 vintage years is required to reliably capture power-law tail returns. A 5-deal portfolio carries unacceptable concentration risk regardless of investor skill.
Staged Check Allocations: Divide your total allocated early-stage capital into an initial check pool (typically 40–50%) and a follow-on reserve pool (50–60%). Reserving capital ensures you can double down on emerging winners during subsequent growth rounds.
Vintage Year Diversification: Market valuations and exit environments fluctuate significantly across macro cycles. Spreading allocations across multiple vintage years smooths out valuation spikes and economic downturns.
3. Sector Focus vs. Structural Hedging
Achieving optimal risk distribution requires balancing sector expertise with concentration limits.
Concentration Limits: Avoid allocating more than 15–20% of total portfolio capital to a single sub-sector or industry niche. Even high-conviction thesis areas can face regulatory shifts, tech transitions, or macroeconomic headwinds.
Synergistic Thesis Clustering: Invest in complementary verticals within your domain knowledge (e.g., panelized manufacturing tech, supply chain telemetry, and prop-tech platforms). Clustering investments within familiar sectors creates network effects that accelerate portfolio value creation.