In an investment landscape dominated by index concentration and mega-cap narrative saturation, the most lucrative risk-adjusted returns rarely sit where mainstream capital flows. While institutional money continues to crowd into high-valuation benchmarks, significant structural shifts are occurring beneath the surface—creating rare asymmetrical entry points for investors with true foresight.
Capital allocations are shifting across key physical and digital bottlenecks. Navigating this environment requires looking beyond surface-level momentum to identify sectors where structural demand, capital re-routing, or severe mispricings yield multi-year tailwinds.
The Base-Load Bottleneck: Energy Infrastructure & The Advanced Nuclear Supply Chain
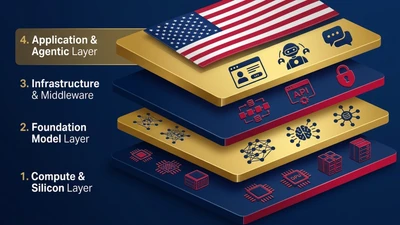
The dominant consensus around artificial intelligence centers almost entirely on compute, software, and hardware scale. However, the true rate-limiting factor for next-generation technology scaling is physical power generation and grid capacity. High-density data centers operating on continuous workloads are straining local electrical infrastructure, driving an unprecedented demand for localized, zero-emission base-load power.
Small Modular Reactors (SMRs) & Advanced Fuel: Early-stage SMR developers and micro-reactor engineering firms represent a generational infrastructure transition. Beyond basic utility plays, key asymmetric upside resides within the fuel enrichment, TRISO fuel fabrication, and specialized nuclear component supply chains. Severe short-term equity pullbacks in early-stage public developers have created deep valuation disconnects relative to long-term tech-sector power purchase agreements (PPAs).
High-Voltage Grid Modernization: The global energy transition and AI expansion require a multi-trillion-dollar rebuild of electrical grids. Pure-play equipment manufacturers supplying transformers, switchgear, and high-voltage grid control technologies hold multi-year order backlogs—providing strong insulation against near-term macro volatility.
Digital Supply Chains: Supply-Side AdTech & Industrial Precision
As broader equity markets slowly broaden beyond mega-caps, niche tech leaders with clear cash flow line-of-sight and proprietary data assets offer compelling entry points.
Supply-Side Targeting & Monetization Platforms: While demand-side advertising platforms face intensifying competition and customer acquisition headwinds, supply-side platforms (SSPs) and publisher-facing adtech infrastructure are capturing outsized value. Media buyers are aggressively moving toward direct supply-side targeting to maximize inventory yield and first-party data privacy compliance.
Critical Minerals & Domestic Supply Security: Geopolitical decoupling has transformed advanced electronic materials, heavy rare earths, and specialized industrial chemicals from cyclical commodities into strategic national security assets. Companies securing domestic refining capacity and advanced material processing trade at substantial discounts to their long-term enterprise replacement costs.
Capital Preservation: High-Moat Staples & Essential Utilities
Rate resets and market concentration have left durable, cash-generative consumer staples and essential municipal assets trading near decade-low multiples relative to their intrinsic cash production.
Essential Water & Municipal Infrastructure: Water security, desalination technology, and specialized municipal wastewater utilities maintain near-absolute pricing power. These high-moat operators deliver predictable earnings, growing defensive yields, and inflation-hedged upside regardless of broader macroeconomic softness.
Specialized Consumer Staples: High-moat, cash-rich consumer defensive operators that were heavily sold off during interest rate hikes now offer prime debt coverage, stable dividend distributions, and strong multi-year re-rating potential as institutional funds seek portfolio defense.
Alternative Assets: Non-Bank Credit & Opportunistic Secondaries
In private markets, standard institutional allocation channels are yielding to specialized non-bank lending strategies and secondary acquisition vehicles.
Asset-Backed Private Lending: With traditional banking channels continuing to tighten lending terms for middle-market operations, non-bank private debt funds targeting short-duration, asset-backed loans continue to deliver high-yield risk-adjusted cash flows with senior-secured debt protections.
Secondary Market Acquisitions: Private equity secondary funds acquiring high-quality venture and growth-stage company equity at deep secondary-market discounts offer structured upside as liquidity cycles normalize.