While financial media spends its energy debating rate-cut quarter-points and worshipping mega-cap tech earnings, a subtle game of musical chairs is playing out under the market floorboards.
If you're only looking at headline P/E ratios and trailing index performance, you’re looking in the rearview mirror right before a hairpin turn. Here is what is quietly brewing on the horizon while consensus looks the other way.
1. The Circular AI Capex Trap & Grid Bottlenecks
Big Tech isn't just funding AI innovation; hyperscalers are creating a closed-loop balance-sheet ecosystem. Cash flows are increasingly supplemented by heavy corporate debt issuance, into companies that turn around and spend that money right back with the lender's compute partners.
The real bottleneck isn't software algorithms—it's physics.
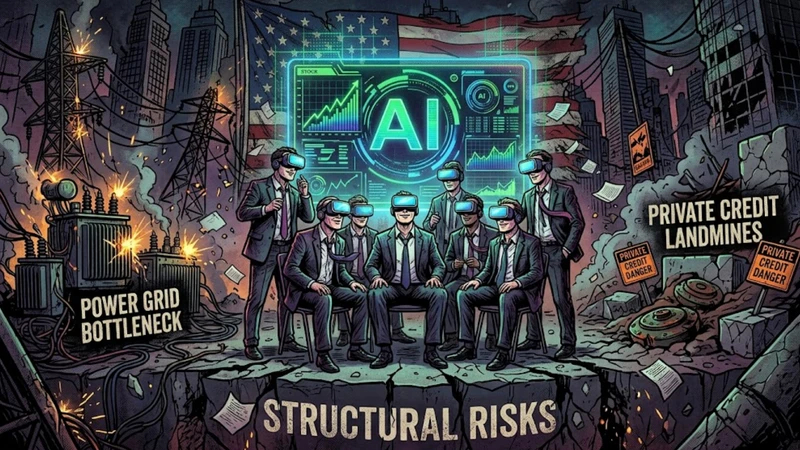
Power Grids & Water: High-density AI execution is slamming into real-world constraints: electrical grid overload, transformer supply shortages, and regional water constraints for cooling.
The Play: The real pricing power isn't coming from another mid-tier AI wrapper; it belongs to utility providers, thermal management engineers, and grid infrastructure builders holding sovereign compute hostage.
2. Private Credit’s Illiquidity Lag
Private credit expanded into a multi-trillion-dollar behemoth precisely because it allowed borrowers and lenders to skip daily mark-to-market discipline. But avoiding price volatility doesn't erase credit risk.
Refinancing Cliffs: Loans underwritten during the zero-rate era are coming due in a structural "higher-for-longer" floor environment.
The Delayed Fuse: Private debt marks update on a quarterly lag via subjective valuation committees. Default stresses in middle-market real estate and leveraged clean-tech builds will take longer to register—until the refinancing door slams shut.
3. The Great Valuation Asymmetry
The broad market index has rarely been this top-heavy. Mega-cap tech dominance has artificially driven top-line index returns, hiding deep discount opportunities across unloved cyclical sectors, healthcare, and high-quality small/mid-caps.
Mean Reversion Ahead: As capital expenditure debt burdens press down on tech margins, dry powder will inevitably look for forgotten cash-flow engines. High-quality mid-caps with fortress balance sheets offer asymmetrical upside if market breadth expands.
Emerging Market Decoupling: Emerging market central banks hiked earlier and cleaner than developed nations. Selective EM local currency debt and regional hubs (spanning Asian trade corridors to Latin American exporters) present compelling real yield spreads at historical valuation discounts.