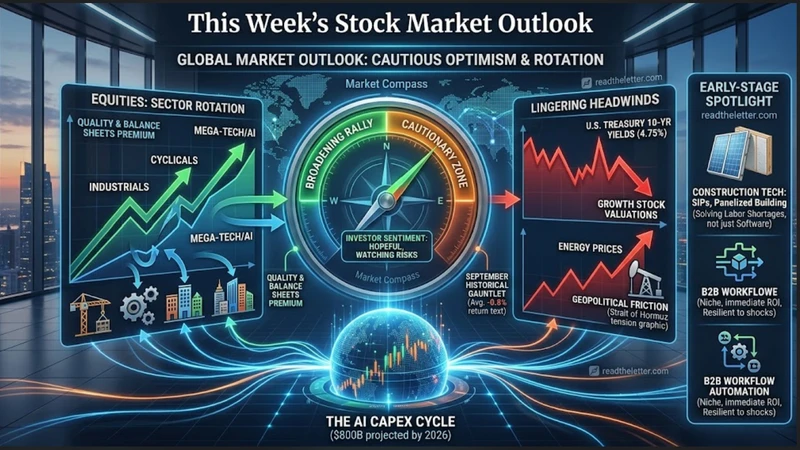
Following a week of resilient economic data, investor sentiment has brightened, yet historical precedent demands caution. September remains notoriously challenging for U.S. equities, averaging a -0.8% return since 1926. While the broad market recently traded at a discount to intrinsic fair value estimates, the macroeconomic environment is tightening.
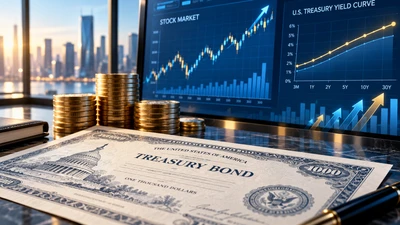
Treasury yields hovering near 4.75% represent a persistent headwind, elevating the discount rate applied to expensive growth stocks and making fixed-income alternatives fiercely competitive. Simultaneously, energy prices face upward pressure driven by geopolitical friction around the Strait of Hormuz, acting as a functional tax on corporate margins and consumer spending.
The AI Capex Cycle and Sector Rotation
Despite yield pressures, structural market themes remain robust. Artificial intelligence has evolved from a speculative frenzy into a massive capital expenditure cycle. Hyperscaler capex is projected to reach roughly $800 billion in 2026, fundamentally reshaping equity, credit, and power markets for years to come.
However, we anticipate capital rotating beyond mega-cap technology into cyclical sectors, industrials, and mid-cap equities. For investors, prioritizing quality, clean balance sheets, and disciplined portfolio construction is paramount in this transition.