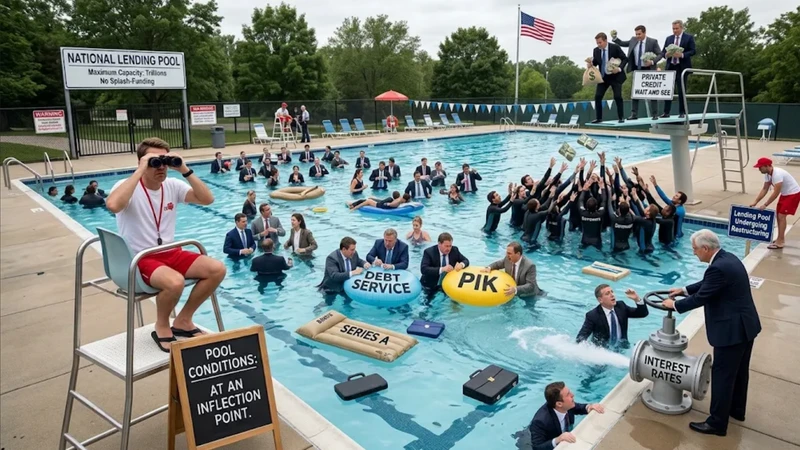
Walk into any investment committee meeting this week, and you will encounter a striking contradiction. On paper, capital is abundant. Venture deployment is surging ahead of last year’s pace, and trillions of dollars in dry powder sit across commercial banks, syndicated loan desks, and private credit funds. Yet beneath the headline liquidity, allocators are operating with extreme caution—creating a market defined by sharp concentration in equity and latent structural tension in debt.
For founders, fund managers, and private allocators, understanding where capital is flowing—and what could suddenly reverse the tide—is essential to positioning portfolios before the calendar turns to 2027.
The Equity Barbell: Mega-Rounds vs. The Series A Wall
The venture and private equity landscape has hardened into a classic barbell dynamic. Total dollars deployed are climbing, but check-writing is heavily concentrated into fewer, outsized rounds.
Conviction at the Top: Tier-1 funds are bypassing traditional milestone pacing to lock up category leaders in AI infrastructure, enterprise automation, and institutional fintech. Mega-seeds of $10M to $20M have become standard for elite teams, while roughly 10% of U.S. Series A rounds this year have crossed $75M—up sharply from a $50M benchmark in 2025. Over the past week alone, capital has flooded into massive rounds across AI agent orchestration, compute infrastructure, and enterprise cybersecurity (including nine- and ten-figure checks for players like Mirendil, Mercor, Torus, LangChain, and Mavria).
Friction in the Middle: Outside the top decile, deal count remains flat to slightly contracted. Founders who secured initial pilot revenue in 2025 are hitting a steep Series A bottleneck if they cannot prove repeatable, high-margin enterprise sales velocity.
LPs Demand DPI Over Markups: With the traditional IPO window still narrow and strategic M&A serving as the primary exit valve, Limited Partners are heavily scrutinizing Distributed to Paid-In Capital (DPI). Paper markups no longer satisfy institutional allocators; emerging managers must demonstrate clear, near-term paths to cash distributions.
The Trillion-Dollar Lending Pool at an Inflection Point
While equity investors chase AI concentration, the multi-trillion-dollar national lending pool—spanning traditional commercial banks, leveraged loans, and direct private credit—is quietly approaching a critical test.
Because the overwhelming majority of middle-market commercial debt and private credit is floating-rate, the Federal Reserve’s return to monetary tightening and the prospect of further rate hikes have compressed borrower margins for error. Average interest coverage ratios across middle-market borrowers have drifted down toward the 2.0x threshold, while trailing 12-month U.S. private credit default rates remain elevated above 6%.
Bank economists are already registering softer business credit conditions heading into early 2027. A decisive shift from abundant credit to a defensive contraction would likely be triggered by one of four catalysts:
Floating-Rate Debt Service Stress: If revenue growth stalls while benchmark rates remain elevated or tick higher, floating-rate borrowers face immediate cash-flow compression. Once interest coverage breaches covenants, lenders pivot overnight from origination to workout mode.
Energy and Inflation Shocks: Any secondary spike in energy or supply chain costs that forces sustained Fed tightening—or drives sovereign Treasury yields higher—would rapidly reprice credit risk premia and pull institutional capital back toward risk-free government paper.
AI-Driven Valuation or Revenue Shocks: Credit markets carry heavy indirect exposure to enterprise software and data infrastructure. Either a sharp correction in AI equity valuations (drying up refinancing exits) or rapid AI displacement of legacy SaaS business models could erode borrower repayment capacity faster than legacy underwriting models anticipated.
Liquidity Mismatches in Semi-Liquid Vehicles: While major money-center banks have buffered their direct risk via senior-secured facilities, a wave of redemption requests in retail-facing private credit vehicles (such as non-traded BDCs or interval funds) would force managers to halt new syndications and widen spreads.
How Fast Does a Credit Turn Happen?
Credit markets do not reprice uniformly; they move in distinct waves based on duration and liquidity:
| Market Tier | Reaction Speed | Primary Mechanism |
| Public High-Yield & Leveraged Loans | 24 Hours – 2 Weeks | Instant repricing via secondary trading and ETF flows following macro prints or major defaults. |
| Short-Term Working Capital (30–180 Day Paper) | 30 – 60 Days | Rapid capital velocity allows originators to observe daily cash-flow shifts and tighten underwriting within a single billing cycle. |
| Private Credit & Direct Lending | 1 – 2 Quarters (3–6 Months) | Illiquid, hold-to-maturity structures delay mark-to-market panic; stress appears first as "pencils down" on new deals and rising PIK amendments. |
| Regional & Commercial Banks | 2 – 4 Quarters (6–12 Months) | Governed by quarterly loan-loss reserve builds, Senior Loan Officer Opinion Survey (SLOOS) tightening, and regulatory exam cycles. |
For allocators watching the horizon over the next 30 to 90 days, the earliest warning signs will not be headline default announcements. Watch CCC-rated high-yield credit spreads (which have already begun widening relative to higher-quality debt), Payment-in-Kind (PIK) interest conversions in private credit portfolios, and SLOOS net tightening surveys. When borrowers start paying interest with more debt instead of cash, the turn is already underway.